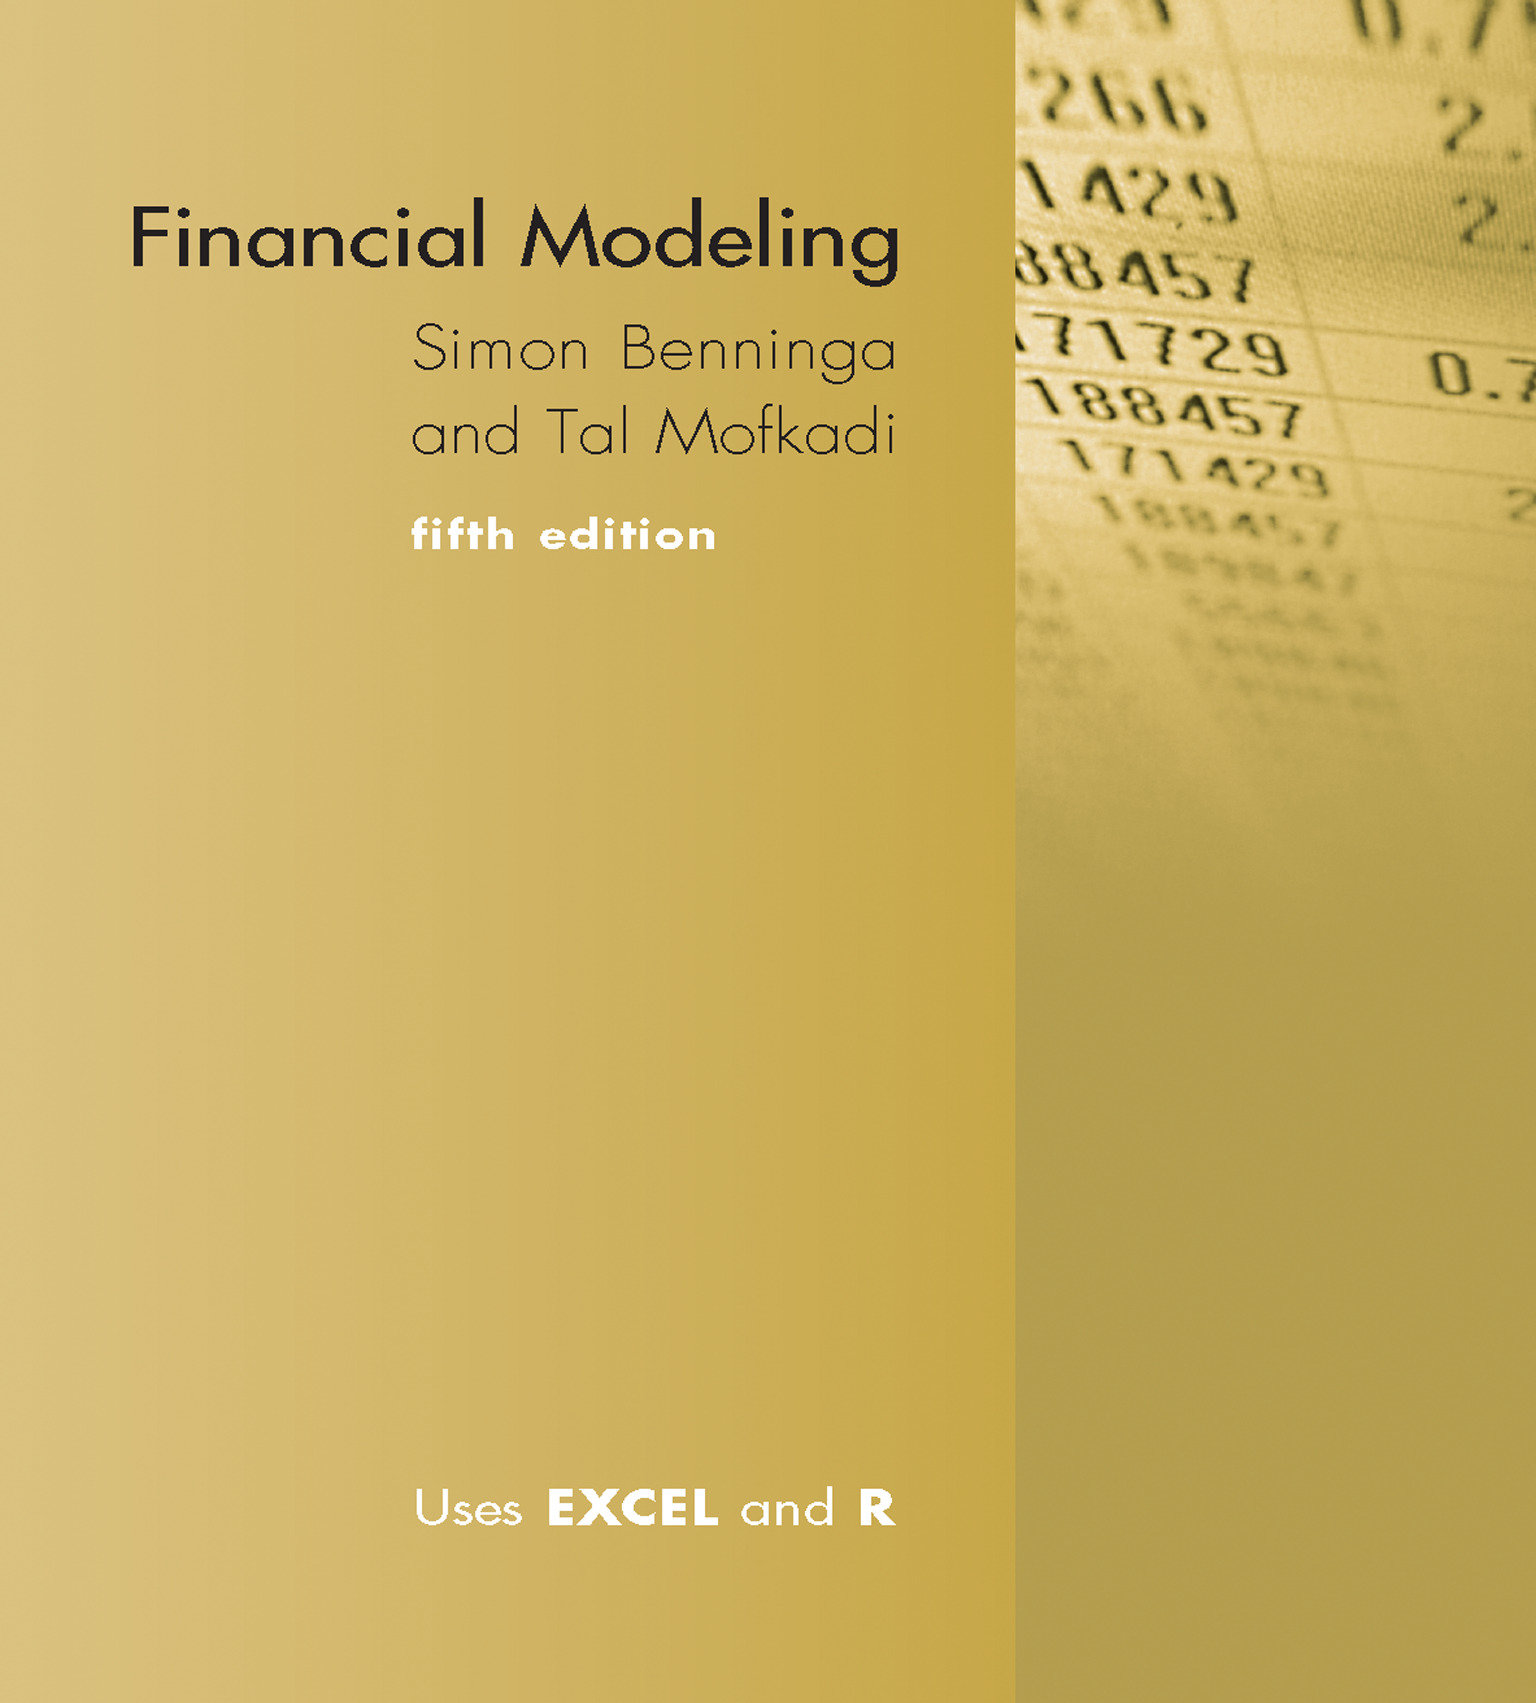
Financial Modeling, Fifth Edition
Kindle Edition
MIT Press · Ebook · February 1, 2022
A substantially updated new edition of the essential text on financial modeling, with revised material, new data, and implementations shown in Excel, R, and Python.
We earn from qualifying purchases.
- Who it’s for
- Explore financial models through explanations and implementations in Excel, R, and Python.
- Genres
- Financial Engineering, Options, Portfolio Management
- Published
- MIT Press, February 1, 2022
Nearest books
Matched by what the books are about, then ordered by what their readers also loved.
 Advanced Modelling in Finance Using Excel and VBAMary Jackson, Mike Staunton73% matchShares Financial Engineering and Options
 Financial Modeling and ValuationPaul Pignataro72% match
 Risk Management and Financial InstitutionsJohn C. Hull66% match
 Venture Capital and the Finance of InnovationAndrew Metrick, Ayako Yasuda64% match
 Lessons in Corporate FinancePaul Asquith, Lawrence A. Weiss64% match
 The Revolution in Corporate FinanceJoel M. Stern, Donald H. Chew, Jr.63% match
 Applied Regression ModelingIain Pardoe61% match
 Corporate FinancePierre Vernimmen, Pascal Quiry61% match
Start with three books, and this one can be the first.
Members get a new edition every morning: a route out from their books to essays, research and talks, with the reason for each.
Start with this bookAbout this book
A substantially updated new edition of the essential text on financial modeling, with revised material, new data, and implementations shown in Excel, R, and Python. Financial Modeling has become the gold-standard text in its field, an essential guide for students, researchers, and practitioners that provides the computational tools needed for modeling finance fundamentals.
Continue reading
This fifth edition has been substantially updated but maintains the straightforward, hands-on approach, with an optimal mix of explanation and implementation, that made the previous editions so popular. Using detailed Excel spreadsheets, it explains basic and advanced models in the areas of corporate finance, portfolio management, options, and bonds. This new edition offers revised material on valuation, second-order and third-order Greeks for options, value at risk (VaR), Monte Carlo methods, and implementation in R. The examples and implementation use up-to-date and relevant data. Parts I to V cover corporate finance topics, bond and yield curve models, portfolio theory, options and derivatives, and Monte Carlo methods and their implementation in finance. Parts VI and VII treat technical topics, with part VI covering Excel and R issues and part VII (now on the book’s auxiliary website) covering Excel’s programming language, Visual Basic for Applications (VBA), and Python implementations. Knowledge of technical chapters on VBA and R is not necessary for understanding the material in the first five parts. The book is suitable for use in advanced finance classes that emphasize the need to combine modeling skills with a deeper knowledge of the underlying financial models.
Finance Models
Explore financial models through explanations and implementations in Excel, R, and Python.
Come here for
- Models in corporate finance, bonds, portfolios, and options
- Monte Carlo methods implemented in finance
Expect
- Revised material on valuation, options Greeks, and value at risk
- Technical topics include Excel and R issues
Where it sits
| Financial Engineering | 80% |
|---|---|
| Portfolio Management | 52% |
| Options | 36% |
Percentages are BookFrontier’s reading of the book.
Publisher categories
- Corporate Finance
- Finance
- Financial Engineering
- Authors
- Simon Benninga, Tal Mofkadi
- Publisher
- MIT Press
- Published
- February 1, 2022
- Format
- Ebook
- Reading lane
- Corporate Finance