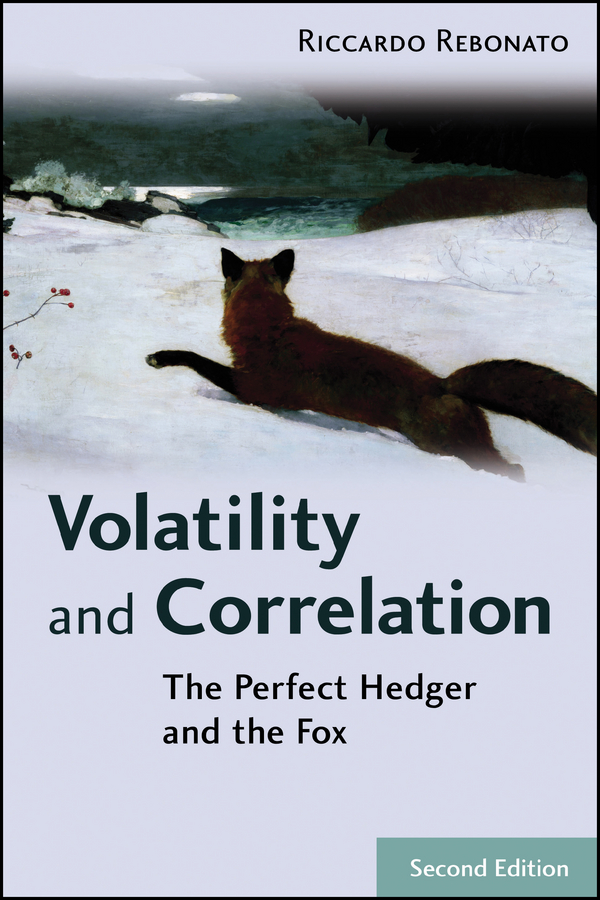
Volatility and Correlation
The Perfect Hedger and the Fox
Wiley · Print & ebook · September 3, 2004
In Volatility and Correlation 2nd edition: The Perfect Hedger and the Fox, Rebonato looks at derivatives pricing from the angle of volatility and correlation.
We earn from qualifying purchases.
- Who it’s for
- Volatility and correlation shape this four-part examination of derivatives pricing and hedging.
- Themes
- Derivatives pricing and hedging, Volatility and correlation modeling, Option-pricing models
- Genres
- Options, Financial Engineering, Financial Risk Management
Nearest books
Matched by what the books are about, then ordered by what their readers also loved. Most of these share its genre: Options.
 Option Volatility Trading StrategiesSheldon Natenberg61% match
 Option TradingEuan Sinclair60% match
 Dynamic HedgingNassim Nicholas Taleb59% matchAlso shares Financial Risk Management
 Understanding OptionsRob Quail, Robert W. Kolb59% match
 The Four Biggest Mistakes in Option TradingJay Kaeppel57% match
 Financial Modeling, Fifth EditionSimon Benninga, Tal Mofkadi57% matchAlso shares Financial Engineering
 Bible of Options Strategies, theGuy Cohen56% match
 Option Trader's Workbook, theJeff Augen56% match
Start with three books, and this one can be the first.
Members get a new edition every morning: a route out from their books to essays, research and talks, with the reason for each.
Start with this bookAbout this book
In Volatility and Correlation 2nd edition: The Perfect Hedger and the Fox, Rebonato looks at derivatives pricing from the angle of volatility and correlation. With both practical and theoretical applications, this is a thorough update of the highly successful Volatility & Correlation – with over 80% new or fully reworked material and is a must have both for practitioners and for students.
Continue reading
The new and updated material includes a critical examination of the ‘perfect-replication’ approach to derivatives pricing, with special attention given to exotic options; a thorough analysis of the role of quadratic variation in derivatives pricing and hedging; a discussion of the informational efficiency of markets in commonly-used calibration and hedging practices. Treatment of new models including Variance Gamma, displaced diffusion, stochastic volatility for interest-rate smiles and equity/FX options. The book is split into four parts. Part I deals with a Black world without smiles, sets out the author’s ‘philosophical’ approach and covers deterministic volatility. Part II looks at smiles in equity and FX worlds. It begins with a review of relevant empirical information about smiles, and provides coverage of local-stochastic-volatility, general-stochastic-volatility, jump-diffusion and Variance-Gamma processes. Part II concludes with an important chapter that discusses if and to what extent one can dispense with an explicit specification of a model, and can directly prescribe the dynamics of the smile surface. Part III focusses on interest rates when the volatility is deterministic. Part IV extends this setting in order to account for smiles in a financially motivated and computationally tractable manner. In this final part the author deals with CEV processes, with diffusive stochastic volatility and with Markov-chain processes. Praise for the First Edition: “In this book, Dr Rebonato brings his penetrating eye to bear on option pricing and hedging.… The book is a must-read for those who already know the basics of options and are looking for an edge in applying the more sophisticated approaches that have recently been developed.” —Professor Ian Cooper, London Business School “Volatility and correlation are at the very core of all option pricing and hedging. In this book, Riccardo Rebonato presents the subject in his characteristically elegant and simple fashion…A rare combination of intellectual insight and practical common sense.” —Anthony Neuberger, London Business School
Smile-Surface Dynamics
Volatility and correlation shape this four-part examination of derivatives pricing and hedging.
Come here for
- Critical scrutiny of perfect-replication pricing, especially for exotic options
- Analysis of quadratic variation in derivatives pricing and hedging
Expect
- Coverage of Variance Gamma models
- Treatment of smile models across equity, FX, and interest-rate markets
Where it sits
| Financial Engineering | 75% |
|---|---|
| Financial Risk Management | 73% |
| Options | 50% |
Percentages are BookFrontier’s reading of the book.
Publisher categories
- Finance
- Investment & Trading Strategies
- Portfolio Management
- Authors
- Riccardo Rebonato
- Publisher
- Wiley
- Published
- September 3, 2004
- Format
- Print & ebook
- Theme
- Derivatives pricing and hedging · Volatility and correlation modeling · Option-pricing models
- Reading lane
- Finance